Capstone Partners Completes Integration of Acquired TM Capital and Select Janney Teams, Unifying the Firm’s Growing Investment Banking Platform. Read More >
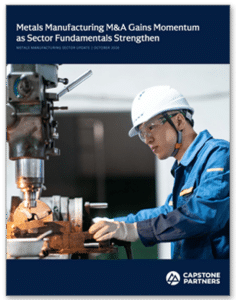
Metals Manufacturing M&A Gains Momentum as Sector Fundamentals Strengthen
Capstone Partners released its Metals Manufacturing M&A Update, reporting that trade policy shifts, domestic manufacturing investments, and strong Aerospace and Defense (A&D) demand have strengthened sector fundamentals year to date (YTD). These trends have also supported a recovery in sector merger and acquisition (M&A) activity and valuation multiples to date, as strategic and financial buyers compete for scaled manufacturers with differentiated capabilities and exposure to attractive end markets.
Tariffs have accelerated the structural overhaul of global metals supply chains and U.S.-based production activity, which began with pandemic-era disruptions and intensified with geopolitical tensions. While U.S. factory construction spending has continued to decline from the peak levels seen in 2024, capital deployment levels remain materially elevated relative to historic norms, with factory construction spending in 2025 totaling 39.7% above the average annual level recorded over the past 10 years, according to the U.S. Bureau of Economic Analysis (BEA) and the Federal Reserve Bank of St. Louis. The sustained investment environment has highlighted demand for domestic manufacturing capacity, supporting order activity and capacity utilization across the Metals sector. Trade policy developments have further reinforced demand, though continued reliance on imported raw materials has kept input costs elevated. At the same time, geopolitical instability has contributed to higher energy costs and broader inflationary pressures, supporting the Federal Reserve’s restrictive monetary stance. Together, persistent raw material inflation and elevated financing costs have compressed margins and increased the importance of scale and operational efficiency, reinforcing strategic and financial acquirer interest in larger, more resilient platforms.
Metals manufacturing M&A dynamics have been shaped by defense-linked demand, supply chain criticality, and the premium buyers have placed on participants serving less cyclical end markets. The fiscal year (FY) 2027 National Defense Appropriations Act (NDAA) proposes $1.1 trillion in discretionary defense spending, including a $95.4 billion increase procurement (+59% YOY) largely fueled by pressure to replenish critical munitions stockpiles, according to U.S. Congress. This has created a powerful demand catalyst for metals producers, particularly high-performance alloys. As a result, qualified vendors serving defense supply chains have commanded outsized valuations. The U.S. Department of War (DOW) awarded IperionX a $47.1 million, two-year contract in February 2025 to develop an integrated domestic titanium supply chain, underscoring the strategic premium now attached to U.S.-based specialty metals capacity serving defense applications. Broader A&D demand has surged, creating an opportunity for specialized equipment providers that have served diversified Industrials end markets. Investors have prioritized targets with aftermarket revenue streams, limited supplier competition, and clear backlog visibility tied to Defense programs.
The rapid deployment of artificial intelligence (AI) infrastructure has created a meaningful demand catalyst for the sector. Investments in semiconductor facilities, data centers, power generation assets, and grid modernization projects have increased structural steel, aluminum, copper, and metal components consumption. Technology companies have committed billions towards expanding computing capacity, and manufacturers serving digital infrastructure markets have benefitted from stronger order activity, improving project visibility, and growing long-term demand pipelines. This trend is expected to support both traditional metals producers and value-added fabricators positioned within the AI and data center space.
Also included in this report:
Analysis of the recovery in Metals Manufacturing M&A activity, including buyer composition, valuation trends, and private equity participation.
A spotlight on A&D-focused manufacturers and the valuation premium commanded by defense-qualified suppliers.
What notable transactions and valuation trends are shaping the 2026 M&A landscape.
Capstone Partners’ Industrials Investment Banking Team provides M&A, capital formation, and financial advisory services to the owners of middle market businesses in the Metals Manufacturing Sector. Our team partners with leading mid-to-large sized businesses that serve growing end-markets.
For more information on the Metals M&A trends featured in this report or to speak with one of our Industrial M&A Team members about how to grow, value, and/or sell your company, we are here to help. Contact us today.